How Insurance Fits into Long Term Financial Planning for Success
If you’ve ever planned for your financial future, you know that it’s more than just saving and investing. There are powerful forces that threaten to undo even the most resilient financial strategies—unexpected accidents, illness, loss of income, or even just the twists and turns of life.
This is where insurance becomes an essential pillar within your long-term financial planning, protecting what you’ve worked so hard to build.
But for many, insurance is seen as an afterthought. In reality, when aligned carefully with your financial goals, it weaves a strong safety net, allowing you to move forward with confidence—no matter what.
The Quiet Protector: Insurance’s Unique Role in Your Plan
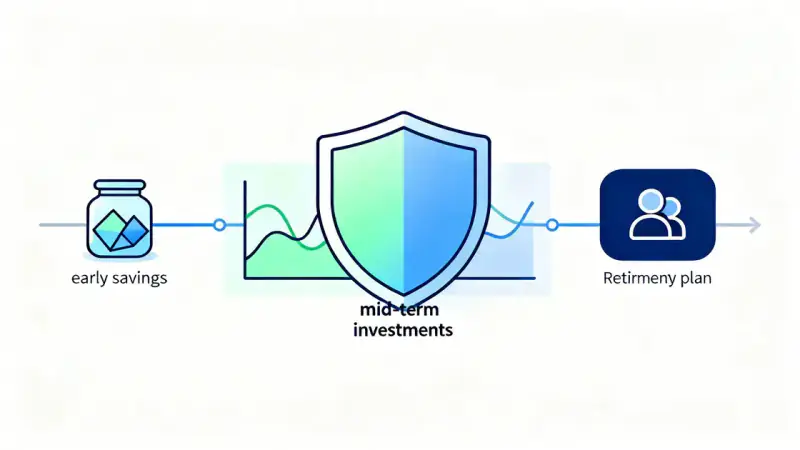
Insurance is often overshadowed by flashier topics like stock investing or real estate. But its role in a robust financial strategy can’t be overstated. Insurance acts as a shield against risks that, if realized, could derail your long-term plans.
Consider the following real-world scenarios:
- An illness or injury strikes, making it impossible to work. Disability insurance can replace lost income so your savings strategy stays on track.
- Unexpected death in the family threatens future educational plans or homeownership dreams. Life insurance provides a payout that ensures your family’s well-being isn’t placed at risk.
- Your home or belongings are damaged by disaster. Property insurance preserves your assets and keeps you from financial ruin.
Without insurance, the financial consequences of such events could erase years of diligent planning in an instant.
Types of Insurance: The Multifaceted Safety Net
Choosing the right coverage is not about having every policy under the sun, but about thoughtful selection to match your risks and life goals. The most common forms of insurance, and how they fit into long-term planning, include:
- Life Insurance – Ensures your loved ones can carry on confidently if you are no longer there to support them. Plans can be term (for a specific period) or whole (lifetime coverage with a cash value component).
- Health Insurance – Medical costs can be devastating without it. Health coverage shields against high medical bills that can destroy net worth and force unwanted debt.
- Disability Insurance – Provides income replacement if illness or injury keeps you from working. Think of it as income insurance during your earning years.
- Property & Casualty Insurance – Protects your possessions, home, and vehicles—guarding what you’ve built over years from sudden loss.
- Long-Term Care Insurance – Covers costs for care in your later years. Preserves your nest egg for yourself and your family instead of draining it on long-term health needs.
The mix and level of insurance you need will shift over time as your career, assets, and family structure evolve.
Integrating Insurance with Wealth-Building Strategies
There’s a misconception that insurance and wealth creation are separate pursuits. In fact, insurance supports your investment goals by limiting downside risks and freeing you to take calculated chances.
For example, if you’re aggressively investing for retirement, a major injury could force you to liquidate assets at a loss if you’re uninsured. But with adequate coverage, you’re able to stay the course and allow compounding to work its magic.
Some life insurance products, such as whole life or universal life, even accumulate cash value that can be used as supplemental retirement income, a loan, or a cushion against unexpected costs. When used deliberately, these hybrid products offer flexibility and can diversify your financial toolkit.
Common Mistakes to Avoid with Insurance in Financial Planning
It’s easy to make errors when incorporating insurance into your financial blueprint. Some pitfalls include:
- Underinsuring because of a focus on cost savings, rather than risk exposure.
- Overinsuring, which wastes resources that could be better allocated elsewhere.
- Forgetting to review and update coverage as life circumstances change (marriage, children, home purchases, career shifts).
- Failing to align beneficiary designations with your estate plan.
- Ignoring inflation, which can erode the value of fixed insurance payouts over decades.
To avoid these, periodically review your insurance portfolio and consult with a professional who understands your long-term vision.
Practical Steps: Incorporating Insurance Into Your Plan
Bringing insurance into your financial master plan doesn’t have to be overwhelming. Here’s an effective approach that blends insight with action:
| Step | Action | Benefit |
|---|---|---|
| 1 | Assess Risks | Identifies vulnerabilities and guides policy choices |
| 2 | Prioritize Needs | Focuses resources on critical risks first |
| 3 | Shop Smart | Ensures value and avoids over- or underinsuring |
| 4 | Review Annually | Keeps coverage aligned with life changes |
| 5 | Integrate With Other Plans | Makes insurance a seamless part of wealth strategy |
By following these steps, you won’t simply buy insurance—you’ll make it a living part of your enduring financial legacy.
Insurance as a Foundation for Confidence and Growth
Perhaps the greatest benefit of understanding how insurance fits into long term financial planning is emotional: the peace of mind to pursue life’s adventures, try new things, and weather setbacks without fear.
Insurance doesn’t eliminate risk, but it gives you the power to bounce back, ensuring that your goals—retirement, education, homeownership—are still possible no matter what the future brings.
Approached thoughtfully, insurance is not just a defensive tool, but a foundation for bold decisions, greater resilience, and true financial freedom. Build it into your plan, review it regularly, and let it work quietly in the background—so you can go forward with hope.